Understanding Personal Loans
Personal loans are a type of installment loan that individuals can use for a variety of purposes, such as consolidating debt, financing large purchases, or covering unexpected expenses. Unlike other forms of credit, such as credit cards, personal loans typically offer a fixed amount of money that is repaid over a predetermined term, resulting in consistent monthly payments for borrowers. This structure can assist in financial planning, as individuals know what to expect in terms of debt repayment over time.
There are primarily two types of personal loans: secured and unsecured. Secured personal loans require the borrower to provide collateral, such as a vehicle or savings account. This reduces the lender’s risk; hence, secured loans often come with lower interest rates. In contrast, unsecured personal loans do not require collateral, meaning they are based solely on the borrower’s creditworthiness. As such, unsecured loans usually carry higher interest rates due to the increased risk for lenders. Understanding these distinctions is crucial for individuals as they consider which type of personal loan best fits their financial situation.
When it comes to personal loans, various essential terms come into play. The interest rate is the cost of borrowing the money, expressed as a percentage of the loan amount, and it can be either fixed or variable. The loan term refers to the duration over which the borrower must repay the loan. Other significant terms include origination fees, which are charges for processing the loan, and the loan amount, which indicates the total sum borrowed. Additionally, understanding the total cost of borrowing, including interest and fees, is critical for making informed financial decisions.
Key Factors to Consider When Comparing Personal Loans
When exploring personal loans, borrowers need to carefully evaluate several key factors to make informed decisions that cater to their financial needs. The comparison process begins with interest rates, which significantly influence the total cost of the loan. Interest rates can vary based on the lender, the borrower’s credit profile, and the loan amount, making it essential to shop around for the best offer. Fixed rates provide stability during repayment, while variable rates may fluctuate, potentially impacting monthly payments.
Loan terms are another critical consideration. The term length of a personal loan typically ranges from one to five years. Shorter terms generally come with higher monthly payments but lower overall interest costs, while longer terms may offer lower monthly obligations but increase the total interest paid over time. It’s crucial for borrowers to choose a term that aligns with their budget and repayment capabilities.
Additionally, examining fees associated with the loan is vital. Many lenders impose origination fees, late payment fees, or prepayment penalties. These fees can considerably affect the total amount payable over the life of the loan. Understanding these charges helps borrowers accurately assess the actual cost of borrowing and avoid surprises during repayment.
Lastly, potential penalties for missed payments can add to the stress of borrowing. Checking the lender’s policies on missed payments ensures that borrowers are aware of the repercussions and can plan accordingly. Taking time to compare different loans based on interest rates, loan terms, fees, and penalties ultimately gives borrowers a clearer picture of their options and their potential impact on personal finances.
Glossary of Loan Terms: APR, Origination Fees, and More
When navigating the landscape of personal loans, understanding the terminology is crucial for making informed financial decisions. One of the most important concepts is the Annual Percentage Rate (APR). The APR represents the total cost of borrowing on a loan expressed as a yearly interest rate. This includes not just the interest charged on the principal amount but also any additional costs, such as certain fees and charges, making it a comprehensive measure of what taking on a loan actually costs.
Another key term to be aware of is the origination fee. This fee is typically charged by the lender for processing the loan application and can vary widely between lenders. The origination fee may be a percentage of the loan amount or a flat fee. Understanding this can significantly impact the total cost of the loan, as it is often deducted from the loan proceeds, meaning the borrower receives less money than was initially agreed upon. This can affect financial planning and budgeting.
In addition to the APR and origination fees, there are other costs associated with personal loans that borrowers should consider. These can include late payment fees, prepayment penalties, and other miscellaneous fees. Each of these can add to the overall expense of the loan and should be factored into the comparison process when evaluating different lending options. Being aware of these terms helps potential borrowers understand the total costs involved throughout the lifecycle of their loan.
Ultimately, a solid grasp of loan terminology, including APR and origination fees, empowers borrowers to make sound decisions by comparing various loan offers effectively. By doing so, individuals can ensure that they choose a loan that aligns with their financial situation and reduces any unnecessary costs associated with borrowing.
Understanding Repayment Periods for Personal Loans
The repayment period of a personal loan is a critical factor that significantly impacts both the monthly payment and the total interest paid over the life of the loan. Generally, personal loans come with repayment periods ranging from one to seven years, although some lenders may offer options extending up to ten years or more. The variation in repayment terms among lenders is influenced by their underwriting criteria, risk assessment, and the borrower’s creditworthiness.
A shorter repayment period typically results in higher monthly payments. However, it also leads to less interest accruing over the life of the loan, which can save the borrower a substantial amount of money. Conversely, longer repayment terms usually result in lower monthly payments, making the loan more manageable on a month-to-month basis. The trade-off, however, is that a longer term can lead to paying considerably more interest overall, which can significantly increase the total cost of the loan.
When considering a personal loan, it is essential to evaluate different repayment options. Some lenders may offer flexibility in choosing the repayment period at the outset or allowing borrowers to pay off the loan early without penalties. This flexibility can be beneficial for borrowers who may experience changes in their financial situation and wish to adjust their payments accordingly. Additionally, understanding the lender’s policies on late fees or missed payments can provide further insights into the overall cost and commitments associated with the loan.
Overall, selecting the right repayment period is crucial in determining the suitability of a personal loan. Borrowers should carefully consider how the repayment timeline aligns with their financial capabilities and long-term goals. It is advisable to use loan calculators provided by many lenders to assess various scenarios, ensuring a comprehensive understanding of how each option affects both monthly payments and total interest commitments.
Credit Requirements for Personal Loans
When applying for a personal loan, understanding the credit requirements set by lenders is crucial. Lenders primarily evaluate a borrower’s creditworthiness through their credit score, which plays a pivotal role in determining not only eligibility but also the interest rates offered. Credit scores typically range from 300 to 850, with higher scores indicating a better credit history. A score of 700 or above is generally considered good and can lead to more favorable loan terms.
Credit scores are calculated based on several factors, including payment history (which accounts for about 35% of the score), amounts owed, length of credit history, new credit, and types of credit in use. Lenders use these metrics to assess the risk of lending money to an individual. Therefore, borrowers are encouraged to maintain a good credit score by making timely payments and minimizing debt levels. However, it’s important to recognize that not all lenders utilize the same criteria when evaluating credit scores.
For individuals with lower credit scores, often due to missed payments or high debt-to-income ratios, options still exist. Some lenders specialize in providing personal loans to borrowers with bad credit. These loans may come with higher interest rates and stricter terms, reflecting the increased risk that lenders perceive. Additionally, secured loans, which require collateral, can be an alternative for those with lower credit scores. This type of loan can offer more favorable terms since the lender has assurance in the form of collateral in case of default.
Furthermore, borrowers might consider applying for a co-signer, who possesses a stronger credit profile. A co-signer helps to alleviate the lender’s concerns about risk, thus increasing the chances of loan approval and potentially securing better rates.
Secured vs. Unsecured Personal Loans
When navigating the world of personal loans, individuals often encounter two primary categories: secured and unsecured loans. Understanding the differences between these two types is vital for making an informed financial decision.
Secured personal loans are backed by collateral. This collateral can take the form of assets such as a car, savings account, or property. If the borrower defaults on the loan, the lender has the right to claim the collateral to recover the owed amount. Typically, secured loans come with lower interest rates compared to their unsecured counterparts. This is largely due to the reduced risk for lenders, as the presence of collateral provides a sense of security.
In contrast, unsecured personal loans do not require collateral, making them inherently riskier for lenders. As a result, interest rates for unsecured loans are generally higher. The approval process for unsecured loans may also be more stringent because lenders primarily evaluate the borrower’s creditworthiness, income, and financial history rather than an asset that can be seized. Borrowers with a strong credit profile may qualify for favorable terms, but those with lower scores might find the options less appealing.
Potential risks for secured borrowers include the loss of their collateral if they’re unable to repay the loan. Conversely, while unsecured loans spare borrowers the risk of losing physical assets, failure to meet repayment obligations can lead to significant financial strain or damage to one’s credit score.
In summary, the choice between secured and unsecured personal loans should align with personal financial circumstances, risk tolerance, and long-term goals. Understanding the implications of each type not only aids in selecting the most appropriate loan but also ensures a better grasp of the financial commitments involved.
Utilizing Online Personal Loan Calculators
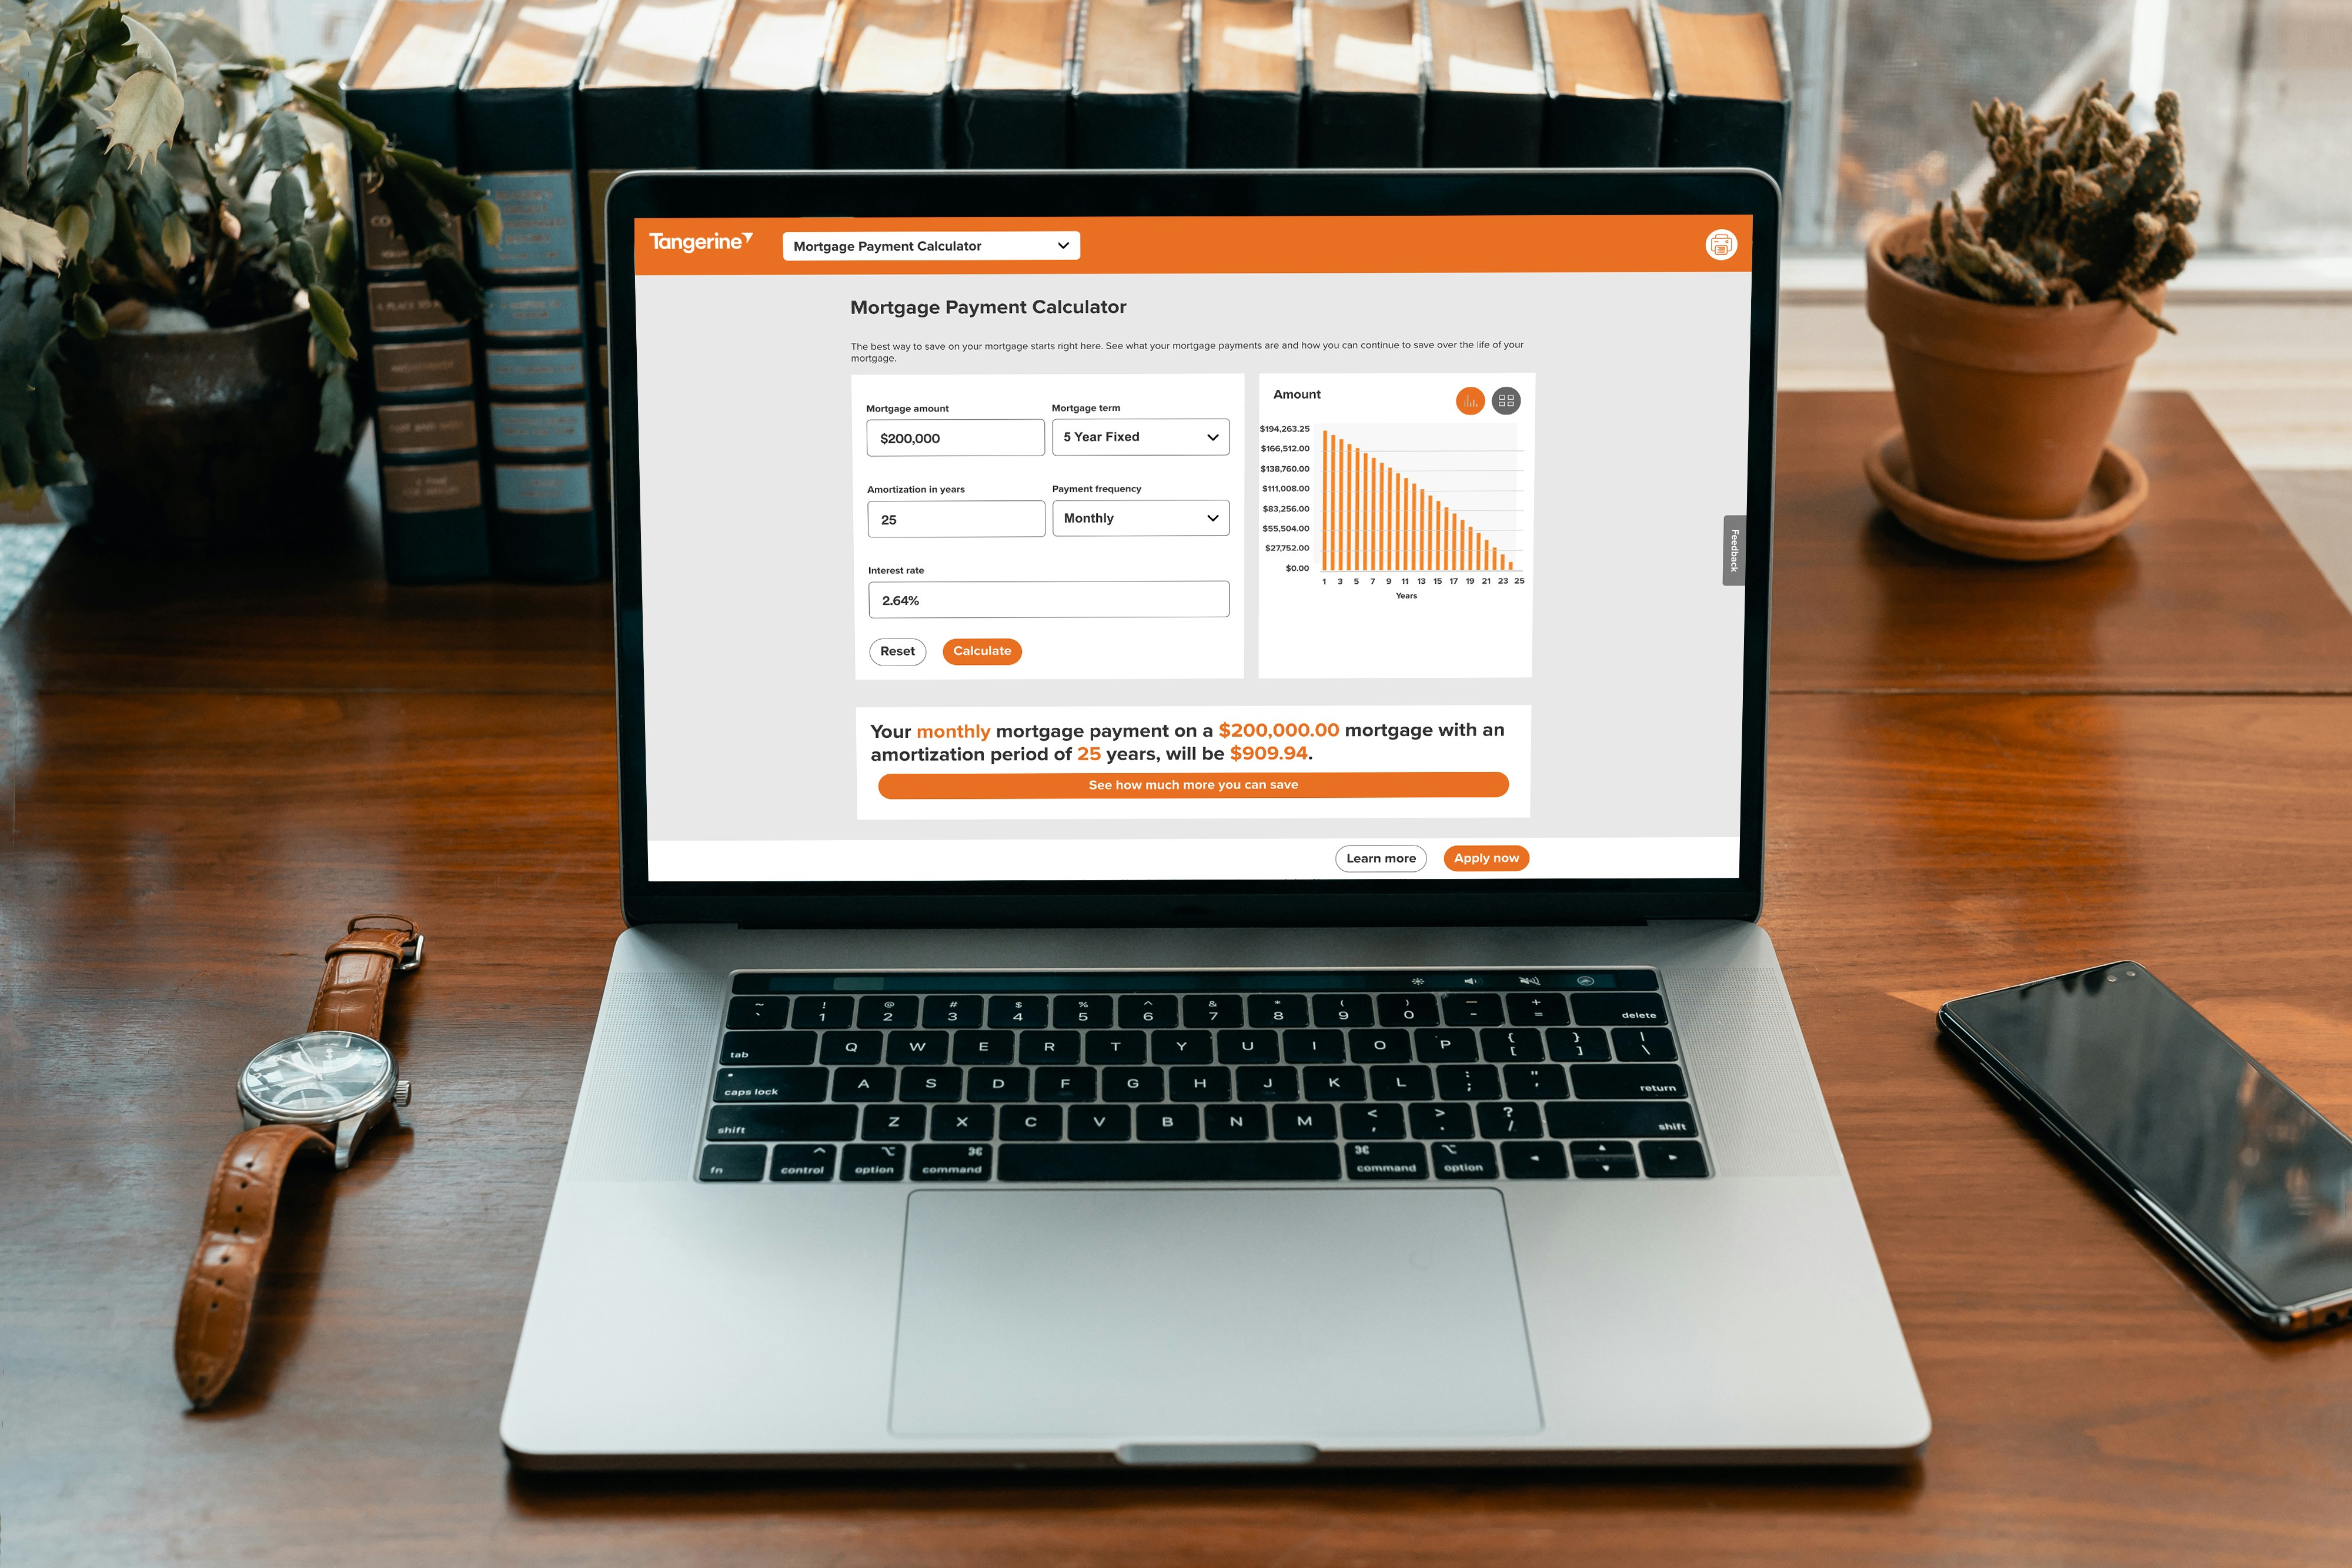
In the realm of personal finance, online personal loan calculators have emerged as essential tools for potential borrowers. These calculators facilitate the process of estimating monthly payments, total interest costs, and overall affordability based on varying loan amounts and terms. By leveraging technology, individuals can make informed decisions before committing to a loan.
Online personal loan calculators allow users to input different variables, such as the desired loan amount, interest rate, and repayment term, to generate an estimate of the monthly payment. This immediate feedback is invaluable as it empowers borrowers to understand the financial implications of their borrowing choices. Furthermore, by adjusting the parameters, users can observe how changes influence their potential payments and total interest accrual.
These calculators typically present various scenarios, enabling users to analyze multiple loan options side by side. For example, if a user is considering loans of different amounts or with varying interest rates, the calculator can quickly display the effects of these factors on the total cost of the loan. This comparative analysis is crucial for identifying the most financially viable option.
Additionally, the information garnered from online personal loan calculators can assist in budgeting, as users can assess their capacity to make payments in accordance with their financial situation. By providing a clearer picture of what repayment looks like under different conditions, borrowers can avoid potential pitfalls associated with entering into a loan agreement without understanding its ramifications.
In summary, utilizing online personal loan calculators can greatly enhance the decision-making process for prospective borrowers. They streamline the assessment of various loan products, helping individuals to compare rates, fees, and terms efficiently. With these tools at their disposal, consumers are better equipped to navigate the often complex landscape of personal loans.
Tips for Comparing Personal Loan Offers
When it comes to securing a personal loan, borrowers should approach the process with a strategic mindset. While interest rates are undoubtedly a significant factor in determining the overall cost of a loan, they should not be the sole criterion for comparison. Here are several actionable tips for effectively comparing loan offers from multiple lenders.
Firstly, consider the annual percentage rate (APR) rather than just the interest rate alone. The APR encompasses not only the cost of borrowing but also includes certain fees, providing a clearer picture of the total loan cost over its duration. By comparing APRs among lenders, borrowers can make more informed decisions.
Next, pay attention to additional fees associated with the loan. These may include origination fees, prepayment penalties, and late payment fees. Understanding these costs is crucial, as they can significantly impact the total amount repaid over the life of a loan. Some lenders may offer lower interest rates but compensate for this through higher fees; therefore, it is essential to evaluate the complete loan package.
Another important factor is the loan terms offered by each lender. This includes the duration of the loan and whether it has flexible payment options. Borrowers should look for terms that suit their financial situation—longer terms may result in lower monthly payments but can lead to greater total interest costs, while shorter terms typically have higher payments but lower overall costs.
Additionally, evaluate the customer service and support each lender provides. A lender with a reputable customer support team can make the borrowing process smoother and ensure that all questions or concerns are addressed promptly. Reviews and testimonials can offer insights into customer experiences with different lenders.
Lastly, taking the time to prequalify with several lenders can help borrowers get an idea of the rates and terms they may be eligible for without affecting their credit scores. By gathering this information, borrowers will be better equipped to find the personal loan that best meets their needs.
Frequently Asked Questions about Personal Loans
When considering personal loans, individuals often have various questions that revolve around the application process, terms, and conditions. Addressing these inquiries can facilitate a smoother borrowing experience. Here are some of the most frequently asked questions regarding personal loans.
What is the typical application process for a personal loan?
The application process usually begins with the borrower submitting a formal request to a lender. This often includes providing personal and financial information such as income, employment status, and existing debts. Lenders will typically conduct a credit check to assess the borrower’s creditworthiness. After evaluation, the lender will communicate their decision, often within a few business days.
Are there prepayment penalties associated with personal loans?
Many lenders do not impose prepayment penalties, allowing borrowers to pay off their loans early without extra fees. However, it is crucial to verify this detail with the lender beforehand, as terms can vary significantly between different financial institutions. Understanding these terms can lead to substantial savings in interest payments.
What should I do if my loan application is rejected?
If a personal loan application is rejected, it is advisable to take a step back and analyze the reasons behind the rejection. Lenders may reject applications due to low credit scores, insufficient income, or high debt-to-income ratios. Improving your credit score, reducing existing debt, or ensuring consistent income can enhance future approval chances. Additionally, borrowers can inquire about the specific reasons for rejection directly with the lender for a clearer understanding.
How long does it typically take to receive funds after loan approval?
Once approved, the timeline for receiving funds can vary, ranging from a few hours to several business days, depending on the lender’s policies and funding methods. Online lenders often provide quicker access to funds compared to traditional banks.
What are the common reasons for personal loan application denials?
Applications are commonly denied for low credit scores, incomplete documentation, high debt-to-income ratios, or lack of credit history. Addressing these factors can significantly improve the chances of approval in future applications.